


For a small restaurant owner in Jakarta, financial innovation becomes meaningful when it helps pay for ingredients, replace a refrigerator or open another outlet. Across Southeast Asia, artificial intelligence is bringing those everyday needs closer to the centre of banking and financial technology.
From lending recommendations to customer support, AI is helping institutions process information and reach customers differently. Its lasting contribution will depend on whether greater convenience also delivers affordable services, reliable protection and fairer access.
Bringing Finance Closer to Small Businesses
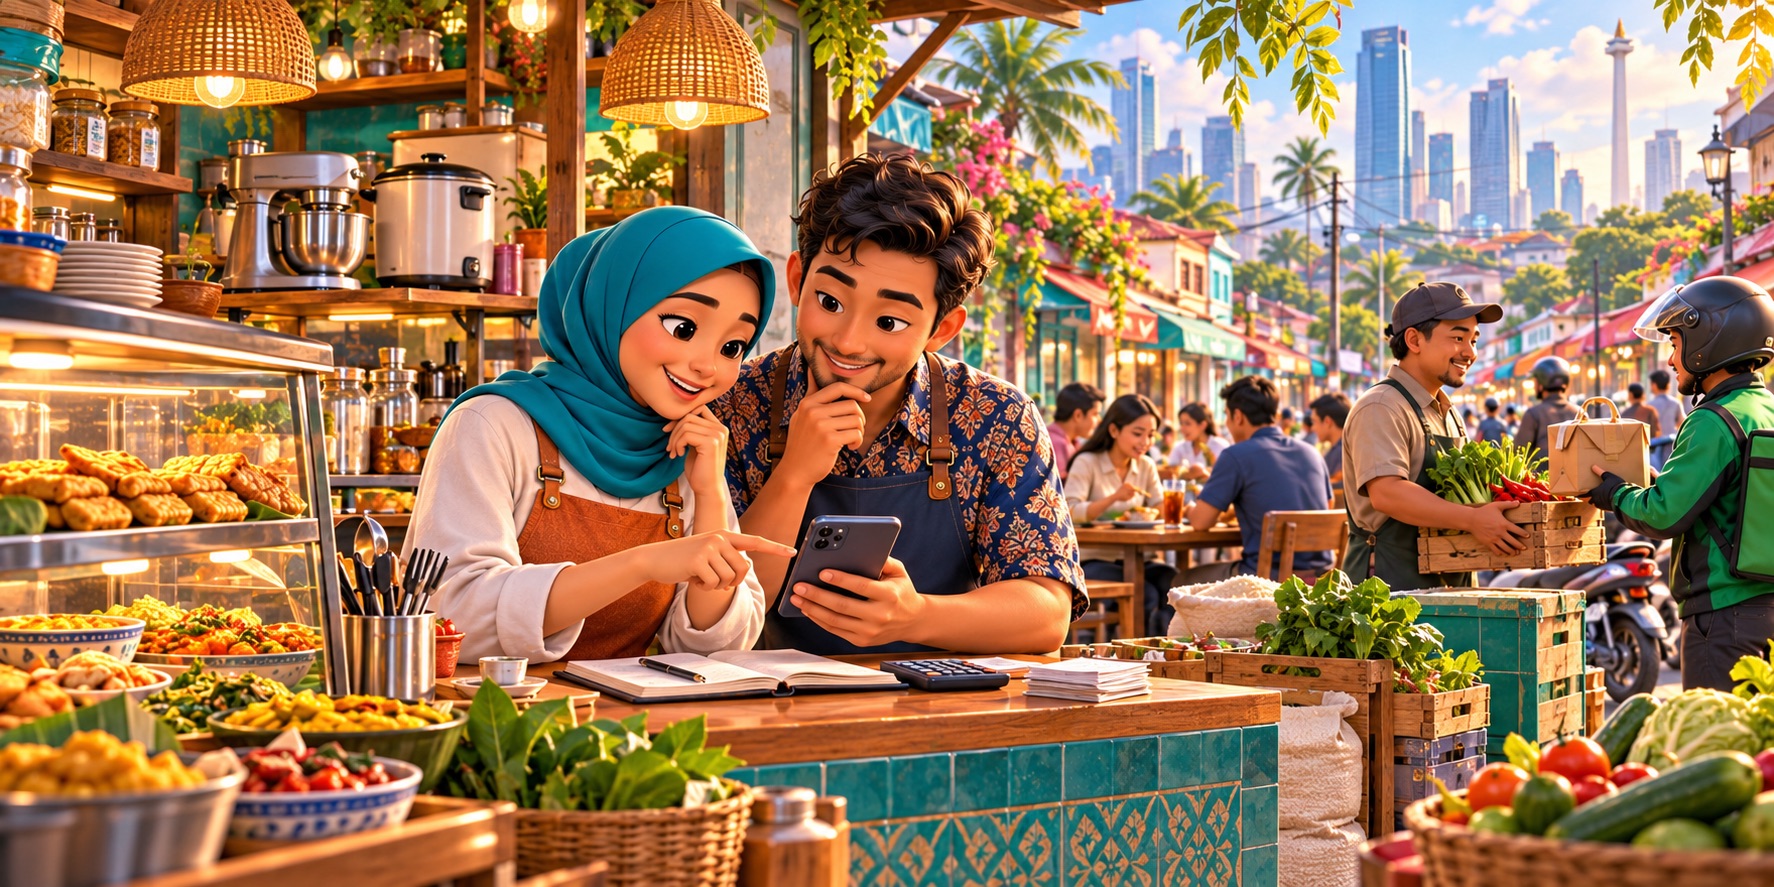
Small businesses often have customers and steady sales but limited documentation for a conventional loan application. Digital platforms can help make those commercial activities visible, creating records that lenders can assess alongside other financial information.
Grab offers a practical example. Its financial services business provides eligible merchants with short-term financing, with repayments deducted from platform earnings. In July 2025, the company described how its AI Merchant Assistant helped merchants explore loan options and receive financing suggestions. Tests covered Indonesia, Thailand and the Philippines.
The company also profiled Jakarta food entrepreneurs Rita and Bang Uyun, who took successive loans of Rp3 million, Rp5 million and Rp10 million to purchase supplies and equipment and expand their business. Their experience illustrates the role of accessible working capital, although it does not establish that AI alone produced the business gains.
At Grab’s April 2025 product showcase, co-founder and Group CEO Anthony Tan described an approach that puts AI into product development “without ever losing sight of who we’re building for”. His remarks concerned the company’s broader technology strategy, a principle equally relevant to its financial services.
For lending, that principle requires more than increasing approvals. A useful recommendation should help a merchant understand repayment obligations and decide whether borrowing fits the business’s cash flow.
Turning Banking Data into Better Services
Established banks are also deploying AI across their operations, offering a clearer picture of the technology’s commercial scale.
Singapore’s DBS reported more than 2,000 AI models across over 430 use cases in its 2025 annual report. The bank attributed approximately S$1 billion in economic value that year to its combined data analytics, artificial intelligence and machine-learning initiatives. This is a company-reported measure encompassing multiple activities, rather than revenue generated by a single AI product.
Its applications include generative AI tools for screening adverse news and DBS Joy, a chatbot providing round-the-clock support to corporate and small-business customers. These uses show how AI can assist both internal work and customer-facing services.
For Southeast Asia’s multilingual markets, the next challenge is making assistance understandable in everyday language. An effective financial chatbot must explain fees and conditions clearly, recognise uncertainty and provide access to a human when a question exceeds its capabilities.
Building Confidence into Digital Finance
The same systems that make financial services faster can introduce new vulnerabilities. An inaccurate recommendation can encourage unsuitable borrowing; an unreliable model can disadvantage customers whose financial lives differ from its training data.
“AI has significant potential to improve financial services,” said Ho Hern Shin, deputy managing director of the Monetary Authority of Singapore, when the regulator issued its AI risk-management guidelines on October 7, 2026. She also emphasised that sustainable benefits require institutions to understand and manage the accompanying risks.
The guidelines address accountability, data governance, testing, human oversight and cybersecurity. They also make clear that financial institutions remain responsible for AI used in their services, including systems supplied by outside providers. Implementation begins in October 2027, with further requirements following in October 2028.
For customers, responsible adoption should translate into practical safeguards: understandable decisions, secure handling of personal information and a meaningful way to challenge mistakes. Those protections are especially important for people entering formal finance for the first time.
Connecting Innovation with Everyday Needs
Southeast Asia’s fintech development brings together several technologies, and identifying their different roles makes the story clearer. Digital payments create transaction records. Payment-network connections enable transfers. AI can analyse patterns, assist decisions or generate responses within those services.
A QR payment is therefore not, by itself, evidence of AI adoption. Similarly, automated investment portfolios may follow predefined rules rather than machine-learning models. The useful question is what a particular system does and whether it improves outcomes.
That distinction also sharpens the meaning of financial inclusion. More accounts and loan offers can expand access, but lasting progress depends on whether people can save securely, borrow affordably, resolve problems and build financial resilience.
Southeast Asia’s strongest AI-finance story will be measured in those everyday outcomes: a business managing its cash flow, a customer receiving a clear answer and a financial system earning trust as it grows.


